

Money
Debt Snowball vs. Avalanche: How to Choose a Payoff Strategy
Compare the debt snowball and avalanche methods, decide where extra payments go, and build a payoff plan you can keep following.
# Debt Snowball vs. Avalanche: How to Choose a Payoff Strategy
When you have several debts, deciding where extra money should go can feel like another problem to solve. Two common approaches are the debt snowball and the debt avalanche. Both keep every account’s required minimum payment current and direct any extra payoff money toward one chosen debt. The difference is how you choose that target.
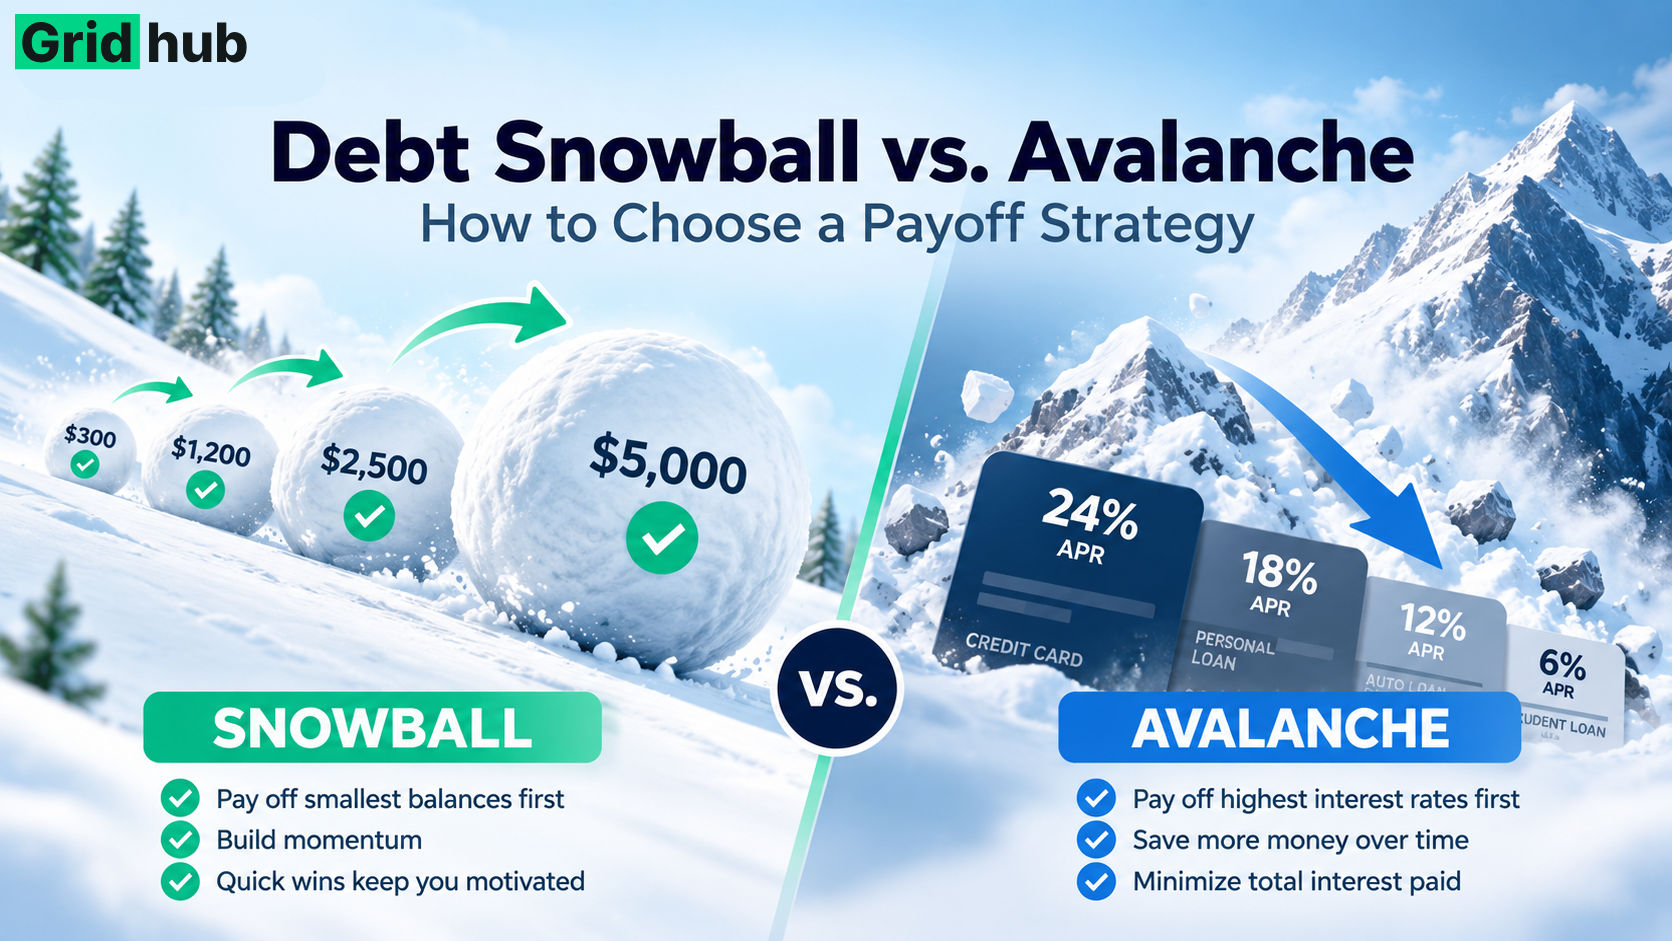
The snowball targets the smallest balance first. The avalanche targets the highest interest rate first. If you can keep the same total payment in place, the avalanche will generally reduce interest cost compared with paying a lower-rate balance first. The snowball can produce an earlier account payoff, which some people find motivating. The best method is the one that fits your numbers and that you can follow consistently.
What is the debt snowball method?
List debts from the smallest current balance to the largest. Pay at least the minimum due on every debt, then put your extra payoff amount toward the smallest balance. Once it is paid off, add the amount you had been paying on it to the payment for the next-smallest debt. Keep rolling that payment forward as each balance is cleared.
The Consumer Financial Protection Bureau (CFPB) describes this smallest-balance approach as a way to build momentum: paying off a debt can make the next one feel more manageable. The tradeoff is that a small balance may have a lower rate than another debt, so interest can continue accumulating on the higher-rate debt while you focus elsewhere. CFPB debt-reduction worksheet
What is the debt avalanche method?
List debts from the highest interest rate to the lowest. Pay at least the minimum due on every account, then send extra payoff money to the debt with the highest rate. After it is paid off, move that full payment to the debt with the next-highest rate.
The avalanche prioritizes the cost of borrowing. If balances, rates, fees, payment timing, and total payments stay otherwise comparable, paying the highest-rate balance first generally means less interest accrues than paying a lower-rate balance first. The CFPB presents this as the highest-interest-rate method and notes that it can save money over time. CFPB debt-reduction worksheet
Snowball vs. avalanche at a glance
| Debt snowball | Debt avalanche | |
|---|---|---|
| First target | Smallest balance | Highest interest rate |
| Main benefit | An account may be cleared sooner, giving you a visible milestone | Directs extra payments toward the most expensive rate first |
| Main tradeoff | May cost more interest if a larger debt has a much higher rate | The first payoff milestone can take longer if the highest-rate debt is large |
| Best fit when | Quick, concrete progress helps you stay engaged | Reducing interest cost is your main priority and you can stay with a longer first target |
Both methods depend on the same foundation: keep required payments current, choose a realistic total amount for debt repayment, and avoid adding new balances where possible. If you cannot make minimum payments, a payoff-order strategy alone will not solve the shortfall; contact your card issuer or lender promptly to discuss options. The CFPB recommends reaching out as soon as you think you may miss a credit-card payment. CFPB: What to do if you can’t pay your credit card bills
Which method may cost less?
The avalanche is usually the lower-interest approach when you can maintain the same total monthly payment and the rate comparison is straightforward. Consider two debts: one has a $600 balance at 8% APR and another has a $4,000 balance at 24% APR. A snowball sends extra money to the $600 balance first. An avalanche sends it to the $4,000 balance first because that debt has the higher rate.
This example shows the targeting rule, not a promise about a specific payoff date or savings amount. Actual interest depends on your lender’s calculation method, payment dates, balance changes, fees, promotional rates, and new purchases. Credit-card issuers may calculate interest using daily balances, and different APRs can apply to different parts of an account. CFPB: How credit-card interest is calculated
A payoff calculator can compare estimates, but treat its result as a planning aid rather than a lender quote. For example, GridHub’s free calculator uses monthly APR divided by 12 and cent rounding; a lender may use daily balance calculations and different payment timing. When comparing plans, use the same debts, minimums, and monthly payment budget in both scenarios.
How to choose a strategy you can stick with
Use the avalanche if you are comfortable waiting for the first debt to disappear and want extra payments to target the highest rate. It may be especially compelling when one rate is much higher than the others.
Use the snowball if clearing a smaller account would make your progress feel real and help you stay consistent. A plan that you follow month after month is more useful than a theoretically cheaper plan that you abandon.
You can also use a hybrid. First, clear one very small balance if that milestone will help you get started. Then switch to the avalanche and target the highest remaining rate. Be clear about the change so you can estimate the cost and know which balance is receiving extra money.
Before choosing, check for unusual terms such as a promotional APR ending soon, deferred interest, prepayment fees, or multiple APR balances within one card. A payment above the minimum on a credit card is generally applied to the highest-APR balance first, subject to applicable rules, but check your statement and card agreement to understand your account. CFPB credit-card interest guidance
Make a simple payoff plan
- List every debt. Record the current balance, APR, minimum due, due date, and any special rate or fee terms.
- Protect minimum payments. Schedule or plan the minimum on every account so your target strategy does not cause missed payments.
- Set a total monthly debt amount. Choose an amount that fits your essential expenses and realistic cash flow. Avoid assuming you can sustain a payment that leaves no room for irregular costs.
- Choose one target order. Sort by balance for snowball or by APR for avalanche. Write down the order so you do not have to make the decision again every month.
- Direct extra money to the current target. After that debt is paid, roll its former payment into the next target while continuing minimums on the rest.
- Review when something changes. Recalculate after a rate change, a payoff, a fee, or a change in income. If you are struggling to make minimums, contact the lender promptly and consider reputable nonprofit credit counseling; be cautious about companies that promise to erase debt or tell you to stop communicating with creditors. CFPB guidance
Keep your estimate realistic
A payoff projection is only as accurate as its assumptions. New purchases, late fees, changing rates, and payment timing can all move the result. The three-year payoff amount printed on some credit-card statements, for example, assumes no new purchases and that you make the displayed payment amount each month. CFPB: Three-year payoff disclosure
Start with the balances and terms you can verify, choose an order, and review the plan as your situation changes. The snowball and avalanche are both ways to organize extra payments; neither replaces making the required payments or getting help when the payment amount is no longer affordable.
Compare your payoff plans
Use the GridHub Debt Payoff Calculator to compare estimated snowball and avalanche schedules. To keep balances and payments up to date over time, use the Debt Payoff Tracker.
---
Sources
- Consumer Financial Protection Bureau, Your Money, Your Goals: Reducing debt worksheet.
- Consumer Financial Protection Bureau, How does my credit card company calculate the amount of interest I owe?.
- Consumer Financial Protection Bureau, What should I do if I can’t pay my credit card bills?.
- Consumer Financial Protection Bureau, Three-year payoff disclosure on a credit-card statement.
This guide is general information for educational purposes. Verify details that depend on your personal circumstances, jurisdiction, or current product terms.
Keep going with GridHub
Put this guide into practice
Use a relevant GridHub tool to put these ideas into action.
Related guides
Money
How to Estimate Your Debt Payoff Time
Estimate when a debt could be paid off using its balance, APR, and payment. Compare fixed-payment scenarios, snowball and avalanche plans, and the lender terms that can change the result.
Money
How to Budget With Irregular Income: A Practical Plan for Low and High Months
Build a flexible budget for freelance, seasonal, commission, or gig income by separating received money from forecasts, protecting essential bills, and planning how to use stronger months.